Evaluation of the Company Size Effect on Latin American Stock Markets
DOI:
https://doi.org/10.17230/ecos.2013.37.1Keywords:
Latin American markets, Size effect, CAPMAbstract
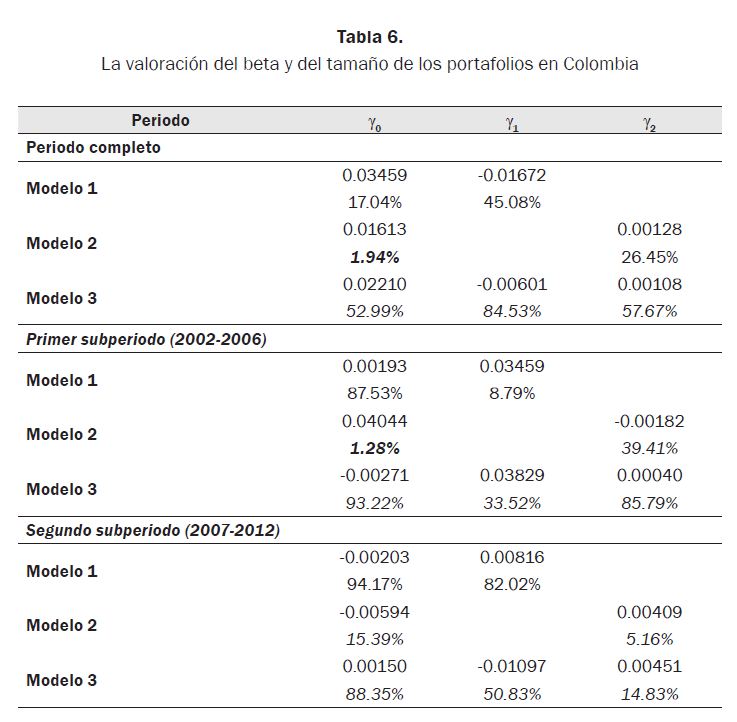
This paper assesses the existence of the size effect on the most important stock markets in Latin America (Argentina, Brazil, Chile, Colombia, Mexico and Peru) for the period between 2002 and 2012, using the cross-section contrast methodology of the size effect in the CAPM context. Results show that there is reversed effect in some of the Latin American markets.
Downloads
References
Multifactor Explanations of Asset Pricing Anomalies (1996). Journal of Finance, 51(1).
Amado, C. (2009). Análisis de la relación entre el comportamiento de la acción y el tamaño de las empresas. Evidencia empírica en Colombia. Bogotá:. Universidad Nacional de Colombia.
Amel-Zadeh, A. (2008). The return of the size anomaly: Evidence from the German Stock Market.. University of Cambridge, Judge Business School Working Paper.
Amihud, Y. (2002). Illiquidity and Stock Returns: Cross-Section and Time-Series Effects. Journal of Financial Markets, 31-56.
Baetge, J.; Kirsch, H.; Koelen, P. y Schulz, R. (2010). On the Myth of Size Premiums in Corporate Valuation: Some Empirical Evidence from the German Stock Market. Journal of Applied Research in Accounting and Finance, 2-15.
Banz, R. (1981). The relationship between return and market value of common stocks. Journal of Financial Economics, 3-18.
Chague, F. (2007). The CAPM and Fama-French Models in Brazil: A Comparative Study. Sao Paulo, Brasil: Escola de Economia de Sao Paulo.
Chan, K.; Chen, N. y Hsieh, D. (1985). An Exploratory Investigation of the Firm Size effect. Journal of Financial Economics, 451-71.
Cohen, R. (2005). Roles del tamaño y del beta en la explicación de los retornos promedio en el mercado accionario Argentino. UCEMA.
Dimson, E. y Marsh, P. (2001). UK Financial Market Returns 1955-2000. Journal of Business, 1-31.
Fama, E. F. y French, K. R. (1992). The Cross-Section of Expected Stock. Journal of Finance, 427-65.
Fama, E. F. y French, K. R. (1995). Size and Book-to-Market Factors in Earnings and Returns. Journal of Finance, 50(1).
Fama, E. F. y French, K. R. (2007). Migration. Financial Analysts Journal, 48-58.
Gómez, J. y Marhuenda, J. (1998). La anomalía del tamaño en el mercado de capitales español. Revista Española de Financiación y Contabilidad, 1033-059.
Hamard, A. y Mascareñas, J. (2010). Prima de riesgo por tamaño en el mercado continuo español. Análisis Financiero, 34-40.
Horowitz, J.; Loughran, T. y Savin, N. (2000). The disappearing size effect. Research in Economics, 83-100.
Ibbotson, R. (2005). SBBI Valuation Edition 2005 Yearbook . Ibbotson & Associates, 127-58.
Keim, D. B. (1983). Related anomalies and stock return seasonality: Further. Journal of Financial Economics, 13-32.
Lucas, R. E. (1978). Asset Pricing in an Exchange Economy. Econometrica, 46, 1429-445.
Reinganum, M. (1981). Misspecification of capital asset pricing: Empirical anomalies based on earnings’ yields and market values. Journal of Financial Economics, 19-46.
Roll, R. (1981). A possible explanation of the Small Firm Effect. Journal of Finance, 879-88.
Ross, S. (1976). The arbitrage theory of capital asset pricing. Journal of Economic Theory, 13(3), 341-60.
Rubio, F. (1997). Corte transversal de los retornos esperados en el mercado accionario chileno. Valparaíso, Chile: Universidad de Valparaíso.
Rubio, G. (1988). Further International Evidence on Asset Pricing: The Case of the Spanish Capital Market. Journal of Banking and Finance, 221-42.
Downloads
Published
Issue
Section
License
Authors who publish with this journal agree to the following terms:
- Authors retain copyright and grant the journal right of first publication with the work simultaneously licensed under a Creative Commons Attribution License that allows others to share the work with an acknowledgment of the work's authorship and initial publication in this journal.
- Authors are able to enter into separate, additional contractual arrangements for the non-exclusive distribution of the journal's published version of the work (e.g., post it to an institutional repository or publish it in a book), with an acknowledgment of its initial publication in this journal.
- Authors are permitted and encouraged to post their work online (e.g., in institutional repositories or on their website) prior to and during the submission process, as it can lead to productive exchanges, as well as earlier and greater citation of published work (See The Effect of Open Access).

